Receiving an insurance settlement offer should feel like a step towards putting a difficult experience behind you. However, what happens if you look at the figure being offered and immediately wonder whether it will actually cover the damage?
For homeowners and businesses dealing with substantial property damage, this can be worrying. Repair costs may be higher than expected, damaged items may need replacing and there could be parts of the loss that you believe have not been fully considered.
An insurance company's first settlement proposal does not necessarily mean that you have to immediately accept it.
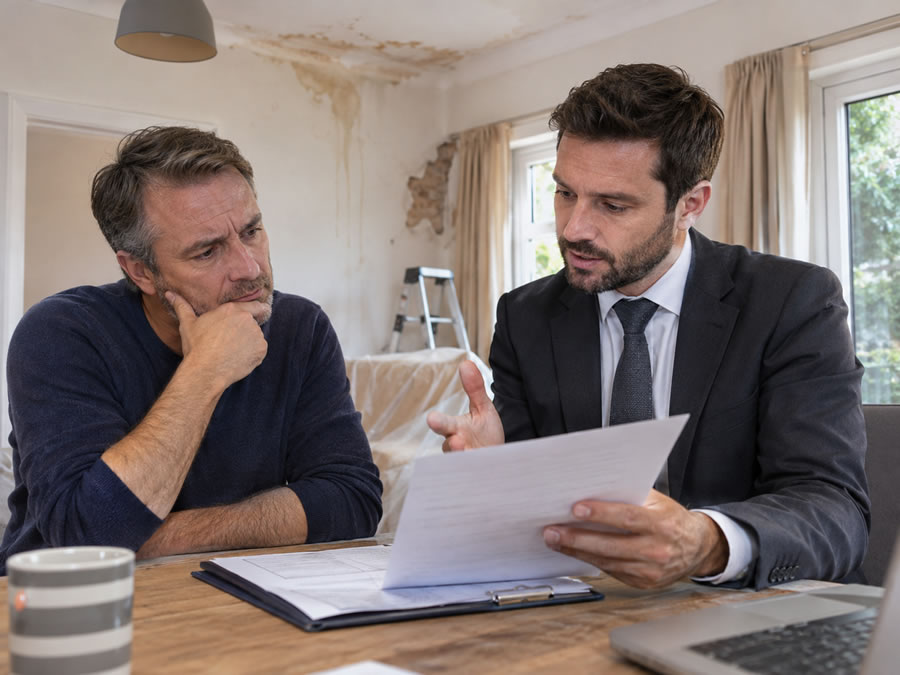
If you believe your insurance settlement is too low, it is important to understand how the figure has been reached and whether all the damage covered by your policy has been properly included.
Why Might an Insurance Settlement Seem Too Low?
Property insurance claims can contain many separate elements.
After a fire, flood, escape of water, storm or burglary, the most obvious damage may only represent part of the overall loss.
For example, water entering a property may damage walls and flooring. However, it could also affect insulation, electrical systems, fitted furniture and possessions. Specialist drying may also be required before repairs can begin.
Similarly, fire damage is not always limited to the area directly affected by the flames. Smoke, soot, heat and water used during firefighting can cause additional damage throughout a property.
If some of these elements have not been identified or correctly costed, the proposed insurance settlement may not reflect the full extent of the claim.
Do Not Feel Pressured to Immediately Accept an Offer
When you receive a settlement proposal, take the time to understand what has been included.
Ask for a clear breakdown where necessary.
Compare the proposed figure with estimates for repairs, replacement costs and any other losses that you believe should be covered under the terms of your insurance policy.
This is particularly important with substantial claims.
Accepting an offer before fully understanding the extent of the damage could leave you facing additional costs later.
If something does not appear correct, it is reasonable to investigate further before deciding how to proceed.
Check Whether All the Damage Has Been Included
One of the first questions to consider is whether the entire loss has been assessed.
Some property damage is immediately visible. Other problems may only become apparent once damaged materials are removed or specialist inspections are undertaken.
Water can travel beneath flooring and behind walls. Smoke can affect areas away from the source of a fire. Storm damage may expose parts of a building to further water ingress.
A proper assessment should therefore consider more than the most obvious cosmetic damage.
At Bell Green Loss Assessors, we assess property damage from the policyholder's perspective and help identify the different elements that may need to form part of an insurance claim.
Obtain Realistic Repair Costs
A settlement figure can only be properly considered when you understand what the necessary repairs are likely to cost.
If you have been given a figure for building work, ask yourself whether suitable contractors can realistically complete all the required work for that amount.
Repair costs may include more than simply replacing the damaged material.
There may be costs associated with removing damaged materials, drying the property, making areas safe, preparing surfaces and completing decoration once the main repair work has finished.
Depending on the circumstances, specialist contractors may also be needed.
Having realistic estimates can provide useful evidence when questioning whether a settlement is sufficient.
Consider Damaged Contents as Well as the Building
With residential claims, furniture, electrical equipment, clothing and personal possessions may also have been affected.
Commercial insurance claims can involve an even wider range of losses, including stock, tools, machinery, office equipment and other business assets.
Keeping a detailed record of damaged items can therefore be extremely important.
Photographs, receipts, valuations and other supporting information may help establish what has been lost and what replacement is likely to cost.
The more complicated the claim becomes, the easier it is for individual items to be overlooked.
What About Commercial Insurance Claims?
A low settlement offer can create particularly serious problems for a business.
Following a significant fire, flood or other insured event, a company may need to repair its premises while also replacing equipment, stock or machinery.
There may also be wider consequences for day-to-day operations.
Business owners understandably want to get trading normally again as quickly as possible. However, rushing into a settlement without considering the complete loss could create financial difficulties later.
Commercial insurance claims can involve substantial documentation and negotiation. Professional assistance can help business owners understand the different elements of the claim and present them clearly to the insurer.
Can You Challenge an Insurance Settlement Offer?
If you believe an insurance settlement does not properly reflect your insured loss, you can raise your concerns with the insurer.
The important thing is to support your position with evidence.
Simply saying that an offer appears too low may not be enough. Building estimates, photographs, inventories, specialist reports and other documentation can help demonstrate why additional amounts should be considered.
You should also understand what your insurance policy actually provides.
Policies contain terms, conditions, limits and exclusions, so any claim needs to be assessed against the cover that was in place when the loss occurred.
How Can a Loss Assessor Help?
This is where the distinction discussed in our previous article, Loss Assessor vs Loss Adjuster, becomes particularly relevant.
The insurer will normally have its own professionals assessing the claim.
A loss assessor represents you.
Bell Green Loss Assessors can review the circumstances of the loss, assess the damage and examine the different elements of the claim from the policyholder's perspective.
We can help gather the information required to support the claim and communicate with the insurer and its representatives on your behalf.
This can be particularly valuable where you are concerned that repairs, possessions or other parts of your insured loss have not been properly recognised.
You Can Seek Help After a Claim Has Started
Some people assume they need to appoint a loss assessor immediately after the incident or they have missed their opportunity.
That is not necessarily the case.
You may already have reported the claim, met the insurer's loss adjuster and received an initial proposal before deciding that you need additional support.
If negotiations are already under way, professional representation may still be possible.
In fact, receiving a settlement proposal that you believe does not reflect the full extent of your loss is often the point at which policyholders begin looking for independent assistance.
Protecting Your Position Before Agreeing a Settlement
The period after serious property damage can be stressful.
You want your home repaired or your business operating normally again, so it can be tempting to accept a settlement simply to move things forward.
However, once repairs begin, unexpected costs can emerge.
Taking time to establish the full extent of the damage, obtain appropriate estimates and understand what has been included in the settlement can help you make a much more informed decision.
Concerned That Your Insurance Settlement Is Too Low?
If you have received an insurance settlement offer and are concerned that it will not adequately cover the insured damage, you do not have to deal with the situation alone.
Bell Green Loss Assessors has been representing policyholders for more than 45 years and deals with both residential and commercial property insurance claims.
Based in Blackpool and working with policyholders across Lancashire, Manchester, Cumbria and the wider North West, our team can assess your loss, help prepare supporting information and represent your interests when dealing with your insurance company.
If your insurance company has made an offer that you believe is too low, seeking professional advice before accepting it could help you understand whether your claim has been properly assessed.
Contact Bell Green Loss Assessors today on our 24hr HELPLINE